
About to retire
Retiring early
Can't wait to retire? Then read all about the most important things to look out for if you want to retire earlier here.
Retiring early: what does that mean?
Not everyone wants to stop working on the pre-determined retirement date. And it is not compulsory either. Retiring earlier gives you time sooner for, for example, a nice trip, voluntary work, a new hobby or your grandchildren. But it also affects your income. So what does retiring earlier mean for your pension income? We explain it on this page.
- More time for a nice trip, voluntary work, a new hobby or your grandchildren
- Less pension accrual, resulting in a lower pension income
This is how you do it
Do you have a pension accrued with Zwitserleven? If so, you can let us know that you want to bring forward your retirement date. There are two options:
Via the form – 6 months before your current retirement date
Is it more than 6 months before you reach your current retirement date? If so, you cannot make this choice in MijnZwitserleven yet. Submit your choice 6 to 3 months before your desired retirement date using this form.
Via MijnZwitserleven – within 6 months of your current retirement date
If your current retirement date is within 6 months, you can submit your choices in MijnZwitserleven. Log in to view your options.
How to choose
Whether retiring earlier is right for you often depends on your personal situation. A financial adviser can help you get an overview of your finances after retirement and advise you on this if you wish. Below is a summary of a few important points:
Pros
-
You may be fitter, which means you can go on to do enjoyable things, such as volunteering, travelling, exercising and looking after grandchildren.
Cons
-
You will accrue less pension, which means you will receive a lower pension income.
-
You may pay more tax if you have not yet reached state pension age.
Right for you if...
-
you reach your state pension age before your retirement date. You can then choose to change your retirement date to the date on which you first receive your state pension.
-
you have an older partner and would like to retire at the same time, and together you have enough financial resources to make up for your lower pension.
-
for medical reasons, you expect not to live to a very old age, which means you need less pension.
-
you already have additional income, for example from an annuity, and free time is more important to you than a higher pension.
Not right for you if...
-
your retirement date is well before your state pension age, and you pay more tax on your pension income.
-
your monthly pension income becomes too low as a result to continue paying your fixed expenses.
-
you may need a loan later on. With a lower pension income, you can borrow less.
-
you expect to live a long time, making it attractive to continue receiving the highest possible pension income. For example, because you may face additional care costs.
-
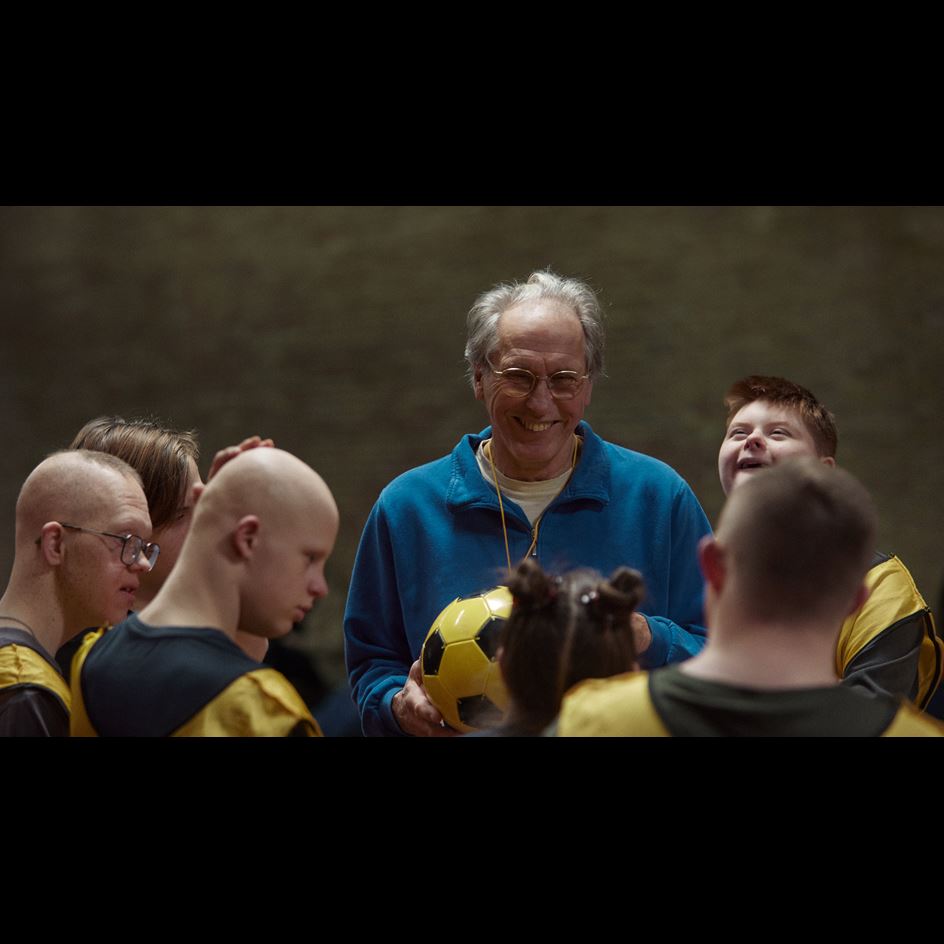
Gerard retired 2 years early
“Retiring early meant I could finally start working full-time as a volunteer at my football club. Together with an adviser, we had calculated what that would mean for my finances. And fortunately, it was possible!”
-
Jane retired 3 years later
“The children had already left home, so I just wanted to keep going for a while longer! My pension wasn’t that high at the time either. By continuing to work for longer, I was also able to build up a bit more pension."
‘My husband had already retired. So retiring early finally gave us the time to do all sorts of things together. And financially, we can manage together, even with my lower pension income.’